FAQ
The questions that come up most, with the answers Chad actually gives. If yours isn't here, it's a text away.
Working with Chad
How do I get in touch with Chad Stallings?
Text or call 602-292-0415 — texting is fastest. You can also email chad.stallings@fairwaymc.com or start an application through his official Fairway Home Mortgage profile. Chad is based at Fairway's Phoenix, AZ branch in Ahwatukee and serves buyers and homeowners across Arizona and New Mexico.
What does it cost to ask Chad a question?
Nothing. Questions, payment estimates, refinance break-even math and pre-approval conversations are free. Lender costs only appear if and when you close a loan, and they are disclosed on your Loan Estimate.
Who is Chad Stallings?
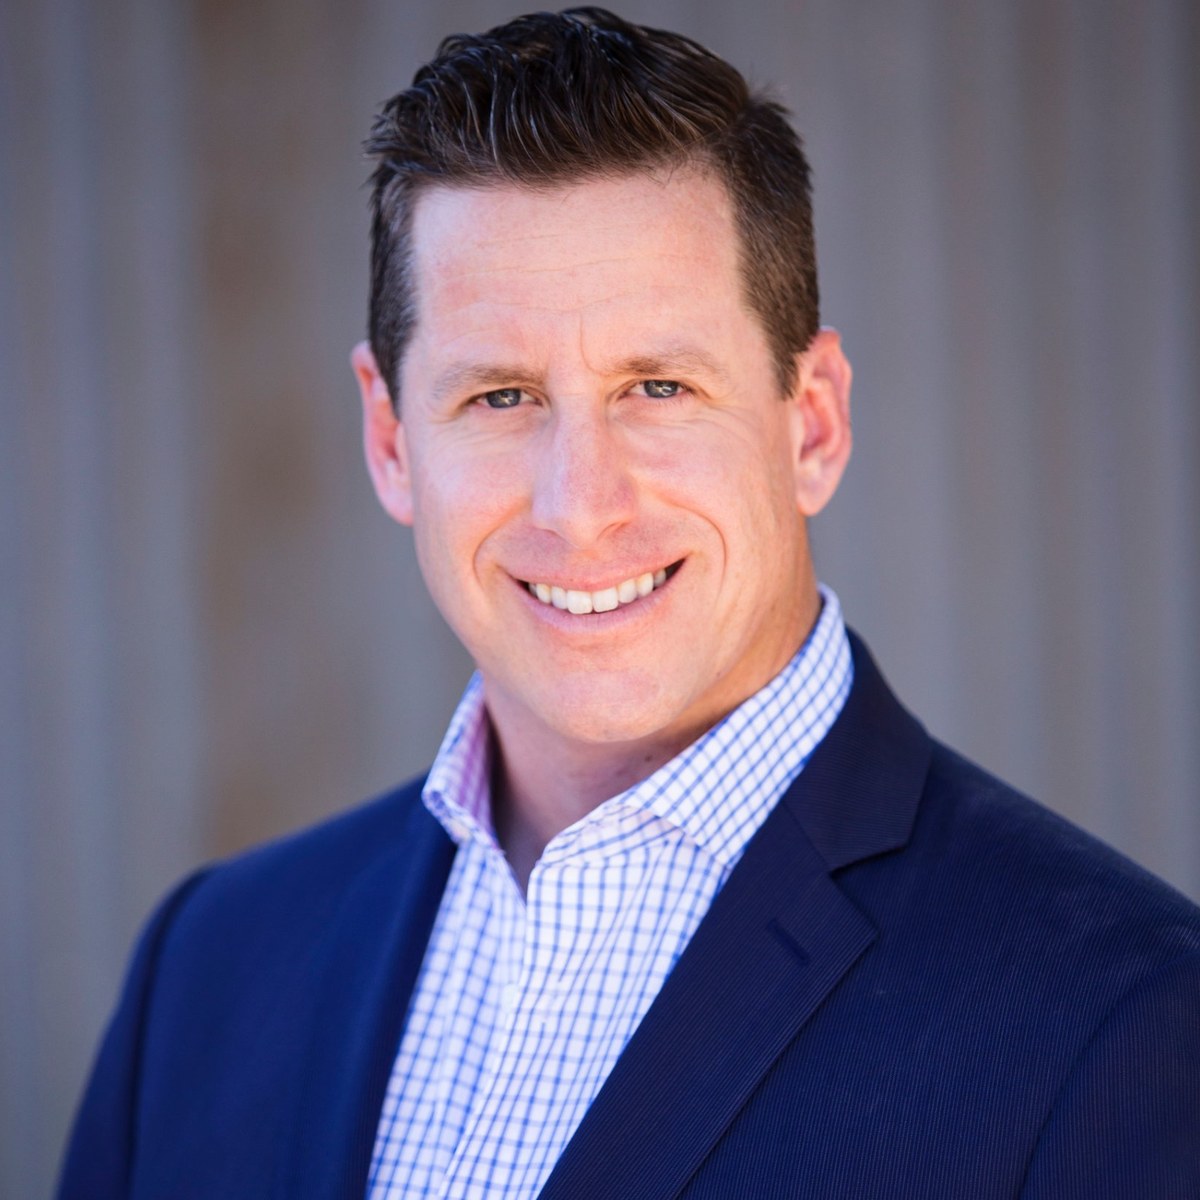
Chad Stallings is a Loan Officer with Fairway Home Mortgage (NMLS #221569) based at the Phoenix, Arizona branch on Agave Road in Ahwatukee, with 25 years in the mortgage business. He works with first-time buyers, move-up buyers, VA buyers and homeowners refinancing across Phoenix, the East Valley, Scottsdale and New Mexico, and is licensed in Arizona and New Mexico.
Do I need a real estate agent to work with Chad?
No — but Chad works best as part of a team with your agent, and he can introduce you to agents he trusts if you do not have one. You are always free to choose any licensed agent.
Does Chad work with my real estate agent directly?
Yes. Chad runs offer-day numbers with your agent, calls the listing agent with every offer, and keeps your agent updated at every milestone so nobody is chasing anyone for status.
Is Chad available on evenings and weekends?
Chad aims to be reachable seven days a week, because showings and offer deadlines do not keep office hours. Text is the fastest way to reach him.
Money questions
How much do I need for a down payment?
As little as 3% on conventional loans for qualified first-time buyers, 3.5% on FHA, and $0 on VA or USDA loans for eligible buyers. Down payment assistance from Arizona HOME+PLUS or Housing New Mexico may cover some or all of it for eligible households.
What credit score do I need to buy a house?
Conventional programs generally start around 620. FHA guidelines allow lower scores with 3.5% down. If your score is not where you want it, Chad can map out what moves it and when buying makes sense.
What will my monthly payment be?
Use the calculator on this site for an instant estimate including principal, interest, taxes, insurance and mortgage insurance. Then text Chad the address and price for numbers specific to that home and your scenario.
What are closing costs?
Fees to finalize the loan and transfer the home — typically roughly 2–4% of the purchase price. They can sometimes be covered partly by seller credits or lender credits, within program limits.
Can my family help with the down payment?
Yes. Gift funds from family are allowed on conventional, FHA, VA and USDA loans with a gift letter and a documented transfer.
Can I buy a house on one income?
Yes. Single buyers and one-income households qualify every day. Lenders look at your debt-to-income ratio, not the number of names on the application, and programs like FHA, USDA and state down payment assistance are built for buyers who qualify on income but are short on savings. Chad built his team around buyers in exactly this spot.
Refinancing questions
Should I refinance my mortgage?
Refinance when the total savings outlast the cost. The quick test: divide the closing costs by the monthly savings — that is how many months until the refinance pays for itself. If you will stay in the home well past that point, it is worth a real look. Chad runs the break-even math for free and will tell you to keep your current loan if that is the better move.
How much does it cost to refinance?
Typical refinance closing costs run roughly 2–3% of the loan amount, and they can often be rolled into the new loan. The exact figure is shown on your Loan Estimate so you can compare the cost to the monthly savings before you decide.
Can I refinance to get rid of FHA mortgage insurance?
Often, yes. With roughly 20% equity, refinancing from an FHA loan into a conventional loan can remove mortgage insurance entirely — sometimes saving hundreds a month even when the rate barely changes.
What is a cash-out refinance?
A cash-out refinance replaces your current mortgage with a larger one and gives you the difference in cash — commonly used for renovations, consolidating higher-interest debt, or other large goals. It is a new first mortgage with its own rate and term, so the break-even math matters just as much as it does for a rate-and-term refinance.
How soon after buying can I refinance?
It depends on the loan program and the type of refinance — some streamline options require a minimum number of payments on the current loan, and cash-out refinances typically require a seasoning period. Chad can tell you the earliest date that makes sense for your loan.
Timing questions
How long does pre-approval take?
Typically a day or two once Chad has your complete documents — often the same day. Incomplete paperwork is the most common delay, which is why the pre-approval checklist exists.
Does getting pre-approved hurt my credit?
A mortgage pre-approval is one hard inquiry — typically a few points, temporarily. Multiple mortgage inquiries in a short shopping window count as one.
How long does it take to close on a house?
Commonly 30–45 days from accepted offer to closing, depending on the contract, appraisal and underwriting. Chad sets a realistic date with you and your agent on offer day.
Should I wait for rates to come down?
Nobody can predict rates. The better question is whether the payment fits comfortably today. If rates fall later, refinancing is an option; the purchase price you lock in today never changes.
Arizona & New Mexico
Is there down payment assistance for home buyers in Arizona?
Yes. The Arizona IDA's HOME+PLUS program pairs a 30-year fixed first mortgage with down payment and closing cost assistance statewide, with no monthly payment on the assistance and no first-time-buyer requirement. Maricopa County buyers can also look at Home in Five Advantage. One program per purchase; Chad checks eligibility and compares them as part of pre-approval.
Is there down payment assistance for first-time home buyers in New Mexico?
Yes. Housing New Mexico (MFA) pairs its FirstHome first mortgage with FirstDown down payment and closing cost assistance for eligible first-time buyers, and FirstDown Plus can add more when funds are available. Income and purchase-price limits vary by county, and homebuyer counseling is required.
Does Chad work with buyers outside the Phoenix metro?
Yes. Chad is licensed statewide in Arizona and New Mexico, so Tucson, Prescott, Payson, Flagstaff, Ruidoso, Alamogordo, Las Cruces, Albuquerque and every town in between work exactly the same way — text, phone, video, secure document upload, and a closing at a title company near you.
Does Chad lend in other states?
Chad is currently licensed in Arizona and New Mexico. If you are buying in another state, he can point you to a licensed Fairway Home Mortgage loan officer there. The current license list is on the disclosures page and on NMLS Consumer Access.
Ready when you are
No dumb questions, no pressure, no forms to fill out. Text Chad what you are wondering about and get a straight answer — usually the same day, nights and weekends included.
Applications happen on Fairway's secure site — never here. Prefer your phone? Get the FairwayNow app.